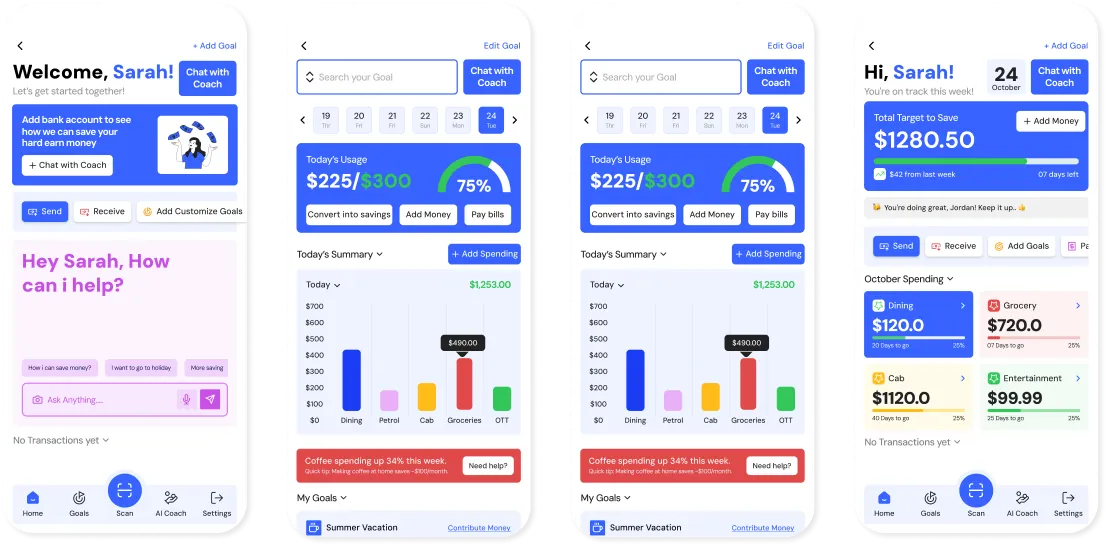
Solving 80% User Abandonment in Budgeting Apps Through Behavioral Psychology & Conversational AI
Market Research
Competitive analysis
Design System
High Fidelity UI
Project
Thryve: AI financial coach
What
Native Mobile App (ios)
Why
Portfolio Project
Role
Research → Designer
Category
Fintech (savings)
When
Oct 2024-Nov 2025
Why I made this project ?
Ever wished your budgeting app actually helped you build money habits-instead of just showing scary numbers and calling it a day? Same. The personal finance app graveyard is massive — 80% of users quit after the first month. That includes me (and most of my friends).
In 2024, I set myself a challenge: could I design an AI-powered money coach that people actually want to use — without guilt, boredom, or overwhelm?
Problem Statement
Most budgeting apps think users are accountants. In reality, we’re human. Apps just say: “Oops, you overspent. Tsk tsk.” Ouch. No actual support, just data dumps and red numbers.
“I love seeing my spending report… until it starts judging me. The guilt kills my motivation.”
How You Reached There: The Story
This journey wasn’t straight lines and sticky notes—it was late-night Reddit, user rants, and a bunch of “aha!” moments.
Overview
Project Goal
Design the first budgeting app that uses behavioral psychology, not just features, to keep users coming back.
Research Part
Design the first budgeting app that uses behavioral psychology, not just features, to keep users coming back.
Analysis
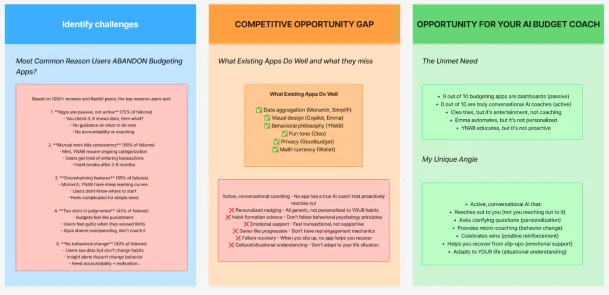
72% think apps are passive (“Show me my data, then what?”) 68%: Stop when manual work builds up (“Who has time to categorize coffee?”) 55%: Overwhelmed by features 45%: Guilt from “red warnings” 40%: “Insight without action” problem
Competitive Analysis
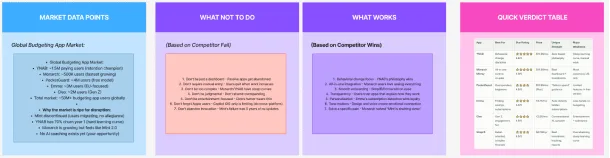
I analysed 3 most popular apps in the space-looking both at the ordering experience and the negative app store comments to find patterns
YNAB
Mint
Monarch Money
The Good:
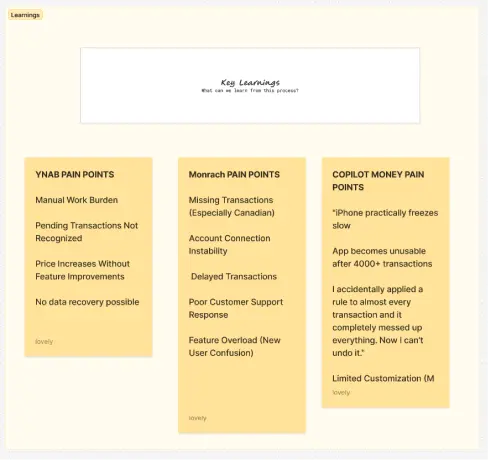
YNAB: Excellent but requires discipline (hardcore users only) Copilot Money: Good UI but no behavioral support Monarch Money: Feature-rich but overwhelming
The Bad:
Manual entry friction – Users don’t type every purchase No accountability buddy – Users feel alone, no encouragement No habit formation – Apps track but don’t teach financial habits
Problem from Comments:
Based on 1,000+ user reviews on App store and Play stor and Reddit analyses, five recurring pain points explain why 70%+ of users churn within the first year:
YNAB works IF you never go over budget. But I’m human. I overspent on groceries by $40 last week—life happens. The app just yells red warnings at me: ‘OVERSPENT: $40.’ No empathy, no ‘let’s fix it,’ just… judgment. It made me feel bad about myself, not motivated to improve. Unsubscribed.
Source: YNAB
Emma L.
Mint was amazing for 2 months. Then I got lazy. I’d miss a few transactions here, forget to categorize there. By month 4, I stopped opening it because the data felt incomplete and useless. I don’t have time to manually log every expense. Life is chaos—why can’t the app just… do it for me? That’s why I deleted it.”
Source: Mint Review
David M.
Tried Monarch Money because everyone says it’s amazing. Got hit with: budget templates, savings goals, expense tracking, investment linking, custom categories, reporting… I literally just want to know where my money goes, not become an accountant. Deleted after 20 minutes. Too many buttons, too many settings. Where do I even start?
Source: Monarch
Reddit
Brainstorming & Ideation
After soaking in hundreds of user rants, it was time for the “kitchen sink” phase. My FigJam board was a mess of wild sticky notes, voting dots, and flows. I don’t just brainstorm for quantity—I go for quirk:
What if receipts could talk back? What if red warnings triggered a virtual puppy instead of shame? Would Gen Z use a budgeting app that looked like a meme?
I ran crazy sketches, listed every pain point, and forced myself to connect dots between “fun” and “finance” (honestly, not that easy).